
Council finance and operations
How to brief a council spend dashboard that reconciles
Follow a parks budget from purchase order to month-end report. Specify the finance definitions, drill-downs and reconciliation evidence a supplier should deliver.
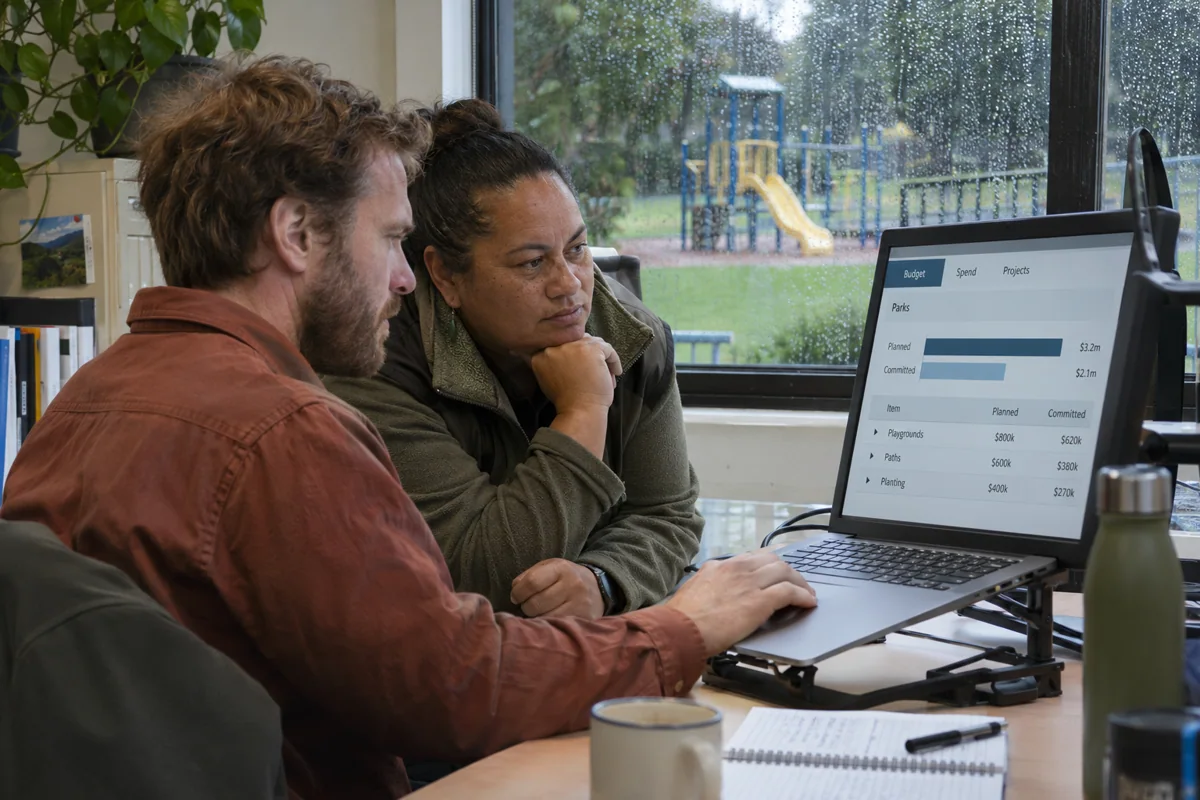
A parks manager wants to know whether there is room in the maintenance budget to repair a playground fence. Finance wants to explain the figure when someone asks about it at a committee meeting. A council spend dashboard can serve both readers if the buyer defines what counts as spent, what remains committed and when the figures were last reconciled. Start the brief with the fence decision and work backwards.
What money is still available?
Give the supplier a fictional NZ$120,000 maintenance budget with NZ$74,000 already posted and NZ$18,000 of open orders. On that basis the uncommitted balance is NZ$28,000. The screen should let the manager see the three inputs, their reporting period and whether they include GST. Ask finance to specify how accruals, transfers and approved variations affect this calculation locally.
Now receive a NZ$6,000 invoice against an existing order. If it moves from committed to actual expenditure in the same period, the available balance should stay at NZ$28,000. Watch how the proposed dashboard handles the interval between the ledger posting and the order update. A report that mixes refresh times can briefly count the same work twice.
Which budget belongs beside the actuals?
Record the budget version alongside every comparison. Ashburton District Council's 2023/24 annual report explains in note 1 why some comparative budgets differ from the published Annual Plan, including the treatment of internal overheads. That concrete example gives buyers a question to ask finance before commissioning a red or green variance indicator.
Have the analyst retain the mapping from the ledger's cost centres to the activity groups people recognise. Choose who approves a change when a depot moves between teams. Preserve the previous mapping for a closed month so that a committee paper can be reproduced after the organisation changes.
How much detail should each reader see?
A budget holder may need a supplier, order reference and coding history to investigate an apparent overspend. An elected member reviewing programme totals may need the approved explanation of that variance. Ask each reader to show where their task ends. That determines which drill-downs deserve investment and which information stays inside the finance system.
Export a closed month to an accessible table with the reporting basis, refresh date and filter choices attached. Give that file to a colleague who never saw the dashboard. Can they explain the fence balance, identify the source and tell whether it is still current?
Ask the supplier to close a month
Supply a sanitised ledger extract, open orders, an agreed budget and the finance team's signed comparison. Include a credit, a late invoice and a line whose activity code is missing. The demonstration should account for every dollar and place the uncoded item somewhere finance can investigate. Assign an owner to that queue and agree what readers see while corrections are pending.
For example, ask the finance analyst to trace a sole uncoded payment from the exception queue through to the corrected total after the next refresh.